Microfinance: Empowering Communities, Alleviating Poverty, and Driving Sustainable Development
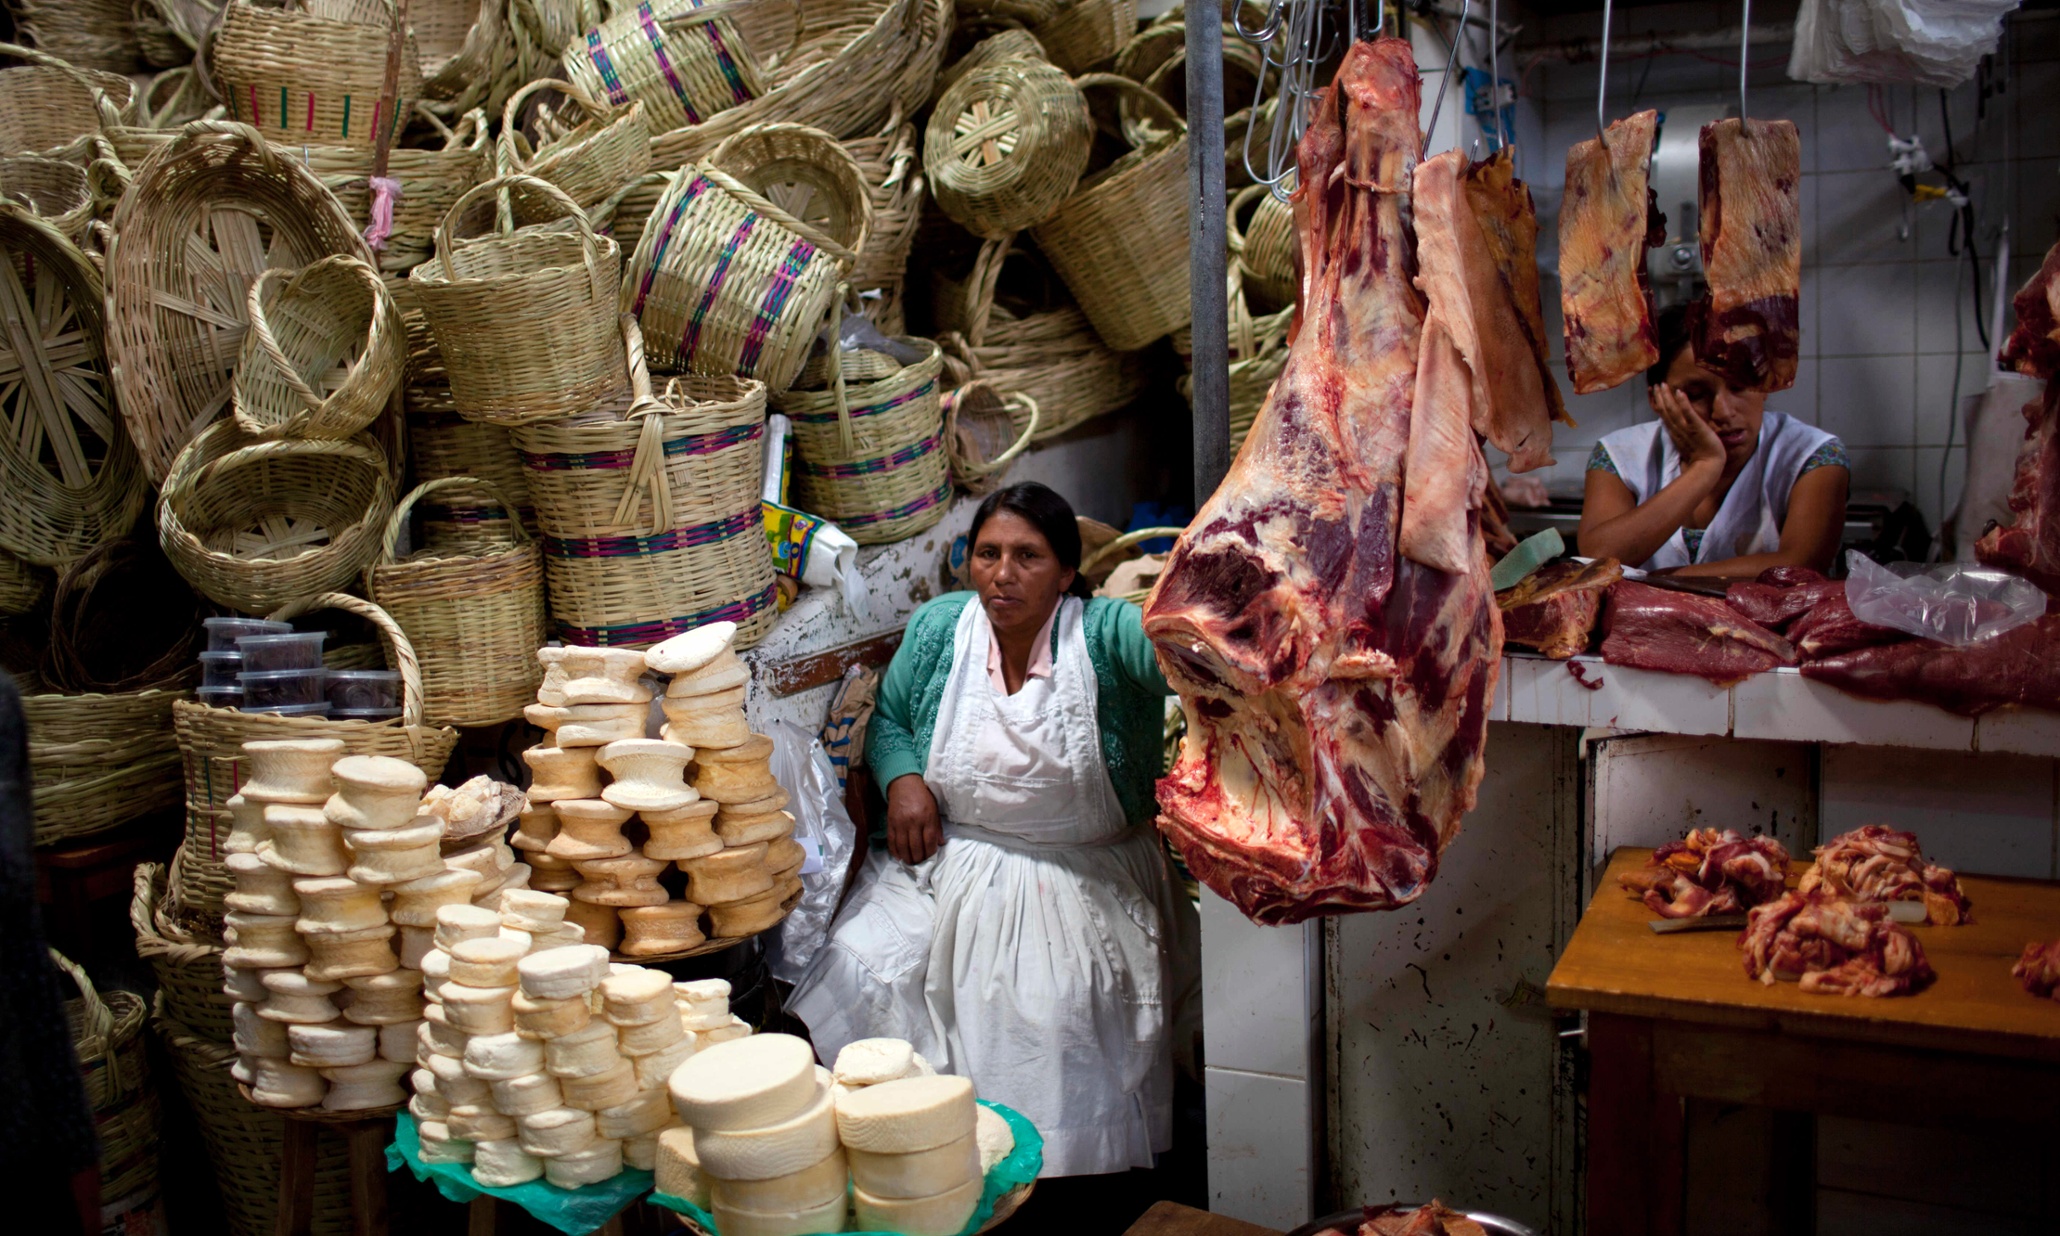
Microfinance for Sustainable Development: Empowering Communities and Alleviating Poverty
Introduction:
In today’s world, sustainable development has become an imperative. As we strive to create a better future for our planet and its inhabitants, it is crucial to address the issue of poverty eradication. Microfinance has emerged as a powerful tool in this fight, offering financial services to those who are excluded from traditional banking systems. By providing small loans, savings accounts, insurance products, and other financial services to low-income individuals and communities, microfinance institutions have been successful in empowering people and fostering sustainable development.
Understanding Microfinance:
Microfinance refers to the provision of financial services tailored specifically for low-income individuals or communities who lack access to traditional banking systems. It aims at alleviating poverty by enabling these marginalized populations to build their own businesses, generate income streams, improve their living conditions, and break free from the cycle of poverty.
Microfinance Institutions (MFIs) operate on the principle that even the poorest individuals have entrepreneurial potential but lack access to capital due to economic barriers such as high interest rates or collateral requirements. These institutions bridge this gap by providing small loans without demanding extensive documentation or collateral security.
The Role of Microcredit in Sustainable Development:
One of the key components of microfinance is microcredit – small loans given primarily for income-generating activities. These loans empower borrowers by allowing them to invest in their businesses or start new ventures. This not only helps boost local economies but also creates employment opportunities within communities.
By supporting entrepreneurship among marginalized groups like women entrepreneurs or rural farmers with limited resources, microcredit plays a pivotal role in addressing gender inequality and rural poverty issues prevalent across many developing countries.
Moreover, studies have shown that when women are empowered through access to credit and other financial services offered by MFIs, they tend to invest more in education and healthcare for themselves and their families – both critical factors contributing towards sustainable development.
Savings Mobilization and Financial Inclusion:
Apart from microcredit, microfinance institutions also promote savings mobilization among low-income individuals. By offering safe and accessible savings accounts tailored to the needs of these communities, MFIs encourage a culture of financial discipline while providing a secure place for storing funds.
Savings mobilization not only helps individuals build assets but also assists in creating capital for future investments or emergencies. It acts as a safety net for vulnerable populations, reducing their dependence on informal moneylenders who often charge exorbitant interest rates.
Furthermore, by promoting financial inclusion, microfinance institutions address the issue of exclusion faced by marginalized communities. Lack of access to financial services perpetuates poverty and hinders economic growth. Microfinance acts as a catalyst in breaking this cycle by bringing these underserved populations into the formal banking sector.
Non-Financial Services: Capacity Building and Social Development:
Microfinance institutions recognize that financial services alone are not sufficient to bring about sustainable development. They understand the importance of capacity building and social development alongside economic empowerment.
MFIs offer non-financial services such as training programs, business development support, vocational training, and entrepreneurship education to equip borrowers with essential skills required to manage their businesses effectively. These initiatives enhance human capital within communities, contributing towards long-term sustainability.
Additionally, many MFIs prioritize social impact over profit maximization. They actively engage with local communities through various activities like health campaigns or environmental awareness programs. By addressing issues beyond finance – such as healthcare access or environmental conservation – they contribute towards holistic sustainable development goals.
Challenges Faced by Microfinance Institutions:
While microfinance has proven to be an effective tool in promoting sustainable development globally, it faces several challenges that need attention:
1. Overindebtedness: Rapid expansion without proper monitoring can result in borrowers becoming trapped under multiple loans from different lenders leading to over-indebtedness.
2. Interest Rates: Balancing sustainability with affordable interest rates remains a challenge for MFIs. Charging high interest rates can be detrimental to borrowers, while low-interest rates may not cover administrative costs and hamper the financial viability of institutions.
3. Governance and Regulation: The microfinance sector requires effective governance structures and regulatory frameworks to ensure transparency, accountability, and consumer protection. These regulations should strike a balance between promoting innovation and safeguarding the interests of vulnerable populations.
4. Impact Assessment: Assessing the social impact of microfinance programs is crucial to evaluate their effectiveness in achieving sustainable development goals. Developing standardized metrics for measuring social outcomes is an ongoing challenge in this field.
Conclusion:
Microfinance has emerged as a powerful tool for sustainable development by empowering marginalized communities with financial services, fostering entrepreneurship, promoting gender equality, and addressing poverty issues worldwide.
By providing access to credit, savings accounts, insurance products, capacity-building initiatives, and non-financial services tailored specifically for low-income individuals or communities who lack access to traditional banking systems, microfinance institutions have played a pivotal role in creating inclusive economies and improving livelihoods.
However, it is essential that we address challenges faced by microfinance institutions such as overindebtedness, interest rates balancing act, governance issues; ensuring effective regulation along with proper impact assessment mechanisms are put in place to continue making progress towards sustainable development through microfinance.
In conclusion, microfinance has proven its potential as an enabler of positive change by bridging financial gaps and empowering underserved populations. It offers hope for a more equitable future where no one is left behind on our journey towards sustainable living and eco-friendly lifestyles